Section 1202 and QSBS planning for founders
The work is done before the exit, not after.
Section 1202 qualified small business stock planning for founders in the District of Columbia, Maryland, and Washington State, whether your gain is likely to sit well under the exclusion cap or above it. We read the statute closely, watch for changes, and tell you plainly what it makes available to you.
QSBS in one minute
What it is. Section 1202 of the tax code lets founders and early investors exclude some or all of the federal tax on the gain when they sell stock in a qualifying small company. That stock is called qualified small business stock, or QSBS.
Who qualifies. Generally, the company is a US C corporation whose gross assets were under a set ceiling when your stock was issued, and it runs an active business. Many service businesses, such as law, health care, and consulting, are excluded. You also need to have received the stock from the company itself, not bought it from another shareholder.
Why timing matters. You have to hold the stock for a minimum period. For stock acquired after 4 July 2025, a partial exclusion begins at three years; earlier stock needs more than five.
How much. The exclusion is capped per company and per taxpayer, at the greater of a fixed dollar amount and ten times what you paid for the stock.
Where trusts come in. Because the cap applies per taxpayer, founders whose gain may exceed it sometimes give stock to separate trusts, each with its own cap. That is what "stacking" means. Most founders do not need it. Nearly all of them need to know their stock qualifies.
Well under the cap? You still have three jobs.
Many founders expect a gain well within the Section 1202 exclusion cap. For them, trust stacking is beside the point, and it is easy to conclude that the statute takes care of itself. It does not. Many founders may never need a SLANT or a separate non-grantor trust for QSBS purposes, but nearly all of them need to know their stock qualifies.
Confirm the stock qualifies
The exclusion is available only if the company and the stock meet every requirement at the right moments. LLC conversions, missed 83(b) elections, redemptions, questions about the active business requirement, and gaps in the corporate record are the usual problems. Most are easier to fix now than at diligence.
Protect the holding period and exit timing
For stock acquired after 4 July 2025, the exclusion is tiered: 50% at three years, 75% at four, and 100% at five. Earlier stock has no exclusion before five years. Many founders hold both, and knowing where each tranche sits shapes how you respond to a tender or an early offer.
Build the family plan
A revocable trust, a pour-over will, powers of attorney, health care directives, and, if you have young children, a named guardian. It is the foundation every founder structure sits on, and many founders do not have one yet.
Early planning keeps more options open. A company comfortably under the cap today can outgrow it after one strong round, and the options for doing something about that are widest while valuations are still low.
Most founder planning is late planning.
Section 1202 rewards structure that exists before value accumulates. The options narrow once a term sheet is signed, and narrow again once a buyer is at the table. Where are you?
Just incorporated or converted from an LLC
The company has just been formed as a C corporation, or an LLC has converted into one.
The risk. After a conversion, the holding period and the gain eligible for exclusion generally start at the conversion date, and an 83(b) election has to be filed within 30 days of a grant.
Priced round or 409A coming
A term sheet, a priced round, or a new 409A valuation is on the way.
The risk. Transfers to family or to trusts are valued when they happen, and a large round can move the company toward the gross-assets ceiling for stock issued afterward.
Tender or secondary sale offered
You have been offered the chance to sell some shares before an exit.
The risk. Which shares you sell and how long each has been held decide what exclusion is available, and some company repurchases can affect the qualification of other stock.
Acquisition interest before year five
A buyer has made an approach before your shares have been held five years.
The risk. Earlier stock has no exclusion before five years and later stock only a partial one, so the timing and form of a deal can matter as much as the price.
Moving between D.C., Maryland, and Washington State
You are moving to, from, or between the District of Columbia, Maryland, and Washington State.
The risk. The three treat marital property, capital gains, and estate taxes differently, so a move can change what a plan does and what it costs.
No estate plan yet
You hold founder equity but have no will, trust, or powers of attorney.
The risk. If something happened to you, a court process could decide who manages the stock and who cares for your children, and any advanced planning has nothing to sit on.
The honest summary: earlier is wider, later is narrower, and it is almost never too late to do something useful.
Who this is for
Founders and early employees who hold qualified small business stock, ideally before a priced round or an exit.
- You hold stock, options, or restricted stock in a US C corporation that may qualify as QSBS, whether you founded the company or joined early.
- A priced round, a tender offer, or acquisition interest may be on the horizon, or has not yet arrived. The options are widest while the stock is still valued low.
- You have a spouse, children, or other family you want provided for, and a basic estate plan that is missing or out of date.
Not sure whether your stock qualifies? That is the first question we answer, in the QSBS Qualification Review. If the stock does not qualify, or a structure is not worth its cost, we tell you.
What the Code makes available
These are the instruments we work with. Which of them fit, and whether any of them fit at all, depends entirely on your facts: the entity, the stock, the holding period, your state of residence, your marital situation, and what you want the money to do. We tell you which apply to you before you commit to the full engagement, not after.
-
Section 1202 qualification review
Before anything is designed, we establish whether the stock plausibly qualifies: entity type, original issuance, the active business requirement, the gross-assets ceiling measured immediately after issuance, redemption history, and the holding period on each tranche. Where the answer is unclear or unfavorable, we say so plainly. A qualification problem found early is often fixable. The same problem found at diligence usually is not.
-
The revocable living trust base
Founder structures sit on top of an ordinary, well-built estate plan: revocable trust, pour-over will, powers of attorney, health care directives, and beneficiary designations that actually match the plan. Advanced structures depend on that foundation, so it is the first thing we check when reviewing a plan built somewhere else.
-
Entity and cap table hygiene
A buyer’s counsel will examine stock certificates, board consents, 83(b) elections, redemption history, and the company’s own records. We work alongside your corporate counsel to make sure the corporate record and documents align with your estate plan and trust structures.
-
Marital property characterization
Washington State is a community property state. The District of Columbia and Maryland are not. Whether stock is separate or community property affects who owns it, how it can be transferred, and what a trust can be funded with. State capital gains, income, estate, and inheritance taxes differ across the three jurisdictions, and each is considered when a structure is designed rather than left to be discovered later.
-
Non-grantor trust planning
A properly structured non-grantor trust is its own taxpayer, with its own Section 1202 limitation, which is why these trusts appear in planning for founders whose gain may exceed one cap. They are heavily conditioned, and they work only if the trust is administered as a genuinely separate taxpayer.
-
SLANT, the spousal lifetime access non-grantor trust
For married founders, a non-grantor trust that keeps a spouse among the beneficiaries. It is a demanding instrument and it is not right for every couple.
Two regimes, divided by one date
The 2025 amendments to Section 1202 apply to stock acquired after 4 July 2025. Stock acquired on or before that date stays under the older regime. Two founders with similar companies can therefore be governed by different numbers, which is why the acquisition date of each tranche is one of the first things we establish.
Acquired on or before 4 July 2025
The prior regime
- Per-issuer exclusion cap
- $10M or 10× basis
- Issuer gross-assets ceiling
- $50M
- Holding period
- 5 years
- Exclusion
-
100%at 5 years
All or nothing at the five-year mark. No partial exclusion below it.
Acquired after 4 July 2025
The current regime
- Per-issuer exclusion cap
- $15M or 10× basis
- Issuer gross-assets ceiling
- $75M
- Holding period
- Tiered from 3 years
- Exclusion
-
50%at 3 years75%at 4 years100%at 5 years
The $15M cap is indexed for inflation beginning in 2027.
Figures stated as of September 2026 and drawn from the statute as currently codified. They are the ceilings the Code sets, not a projection of what any particular shareholder may exclude, which depends on whether the stock qualifies at every relevant moment and on the law in force when it is sold.
How trust structuring actually works
Founders whose gain may exceed one cap hear the word "stacking" and usually hear a number attached to it. We would rather explain the mechanism, because the mechanism is what determines whether a structure holds up. If your expected gain sits well under one cap, this is background rather than a plan.
In brief, the exclusion limitation applies per taxpayer and per issuer, so a trust that is genuinely a separate, non-grantor taxpayer has a limitation of its own. Whether it holds up turns on how the trust is drafted, funded, and administered.
The four points where a structure works or quietly fails
We will not tell you what you will save, and we would be cautious about anyone who does.
The exclusion available under Section 1202 depends on facts that are not yet settled when the planning is done, including whether the company qualifies at any given moment, whether a sale ever happens, what form it takes, what the law says on that date, and how the IRS views the structure on examination. What we can do is explain what the statute makes available, build the structure carefully, document the reasoning, and keep it maintained so the position is defensible if it is ever questioned.
Four stages, one flat-fee quote before any work begins
You will know the scope and the price before you engage. If the qualification review shows that the planning you came in for is not available to you, we will tell you that at the end of stage one rather than build something anyway.
-
Qualification and intent
We review the entity, the stock, the holding periods, your state of residence, and what you want to accomplish. The output is a plain statement of what is and is not available to you. This typically takes one to two weeks.
-
Structure design
We propose a structure, explain the trade-offs including access, irrevocability, cost, administrative burden, examination risk, and the state capital gains, income, estate, and inheritance taxes in play, and confirm your decisions in writing before drafting starts.
-
Drafting and review
Documents are drafted and then reviewed against the authorities they rely on, against your confirmed intent, and against the corporate record, before they reach you for signature.
-
Execution, funding, and upkeep
We coordinate signing, prepare the transfer paperwork, process what institutions will accept from us, and track every asset until it is confirmed. A single structure typically runs six to ten weeks to funded; a multi-trust build typically takes ten to sixteen weeks.
How fees work
Fees are discussed on the first call, once the situation is clear.
A flat fee is quoted in writing before any drafting begins with no hourly billing and no open-ended estimate. Once quoted it does not move unless you change the scope.
The qualification review is itself quoted up front, so you are never billed into a decision you have not made.
What you leave with
A written statement of what is and is not available based on your facts. Executed documents, with the reasoning behind them recorded. A funding schedule tracked asset by asset until each one is confirmed. And a named contact to consult when the statute moves or your company changes.
Timelines are typical rather than promised. They depend on how quickly your company, its custodians, and its transfer agents respond, which is outside the firm's control.
What a typical engagement includes
Each piece is included only where your facts support it. Many founders need only the first.
A revocable living trust
The foundation: a revocable trust, pour-over wills, powers of attorney, health care directives, and guardian nominations for minor children, with a plan for moving your assets into the trust, including your shares where the company's documents allow.
A spousal lifetime access non-grantor trust, where it fits
For some married founders, a non-grantor trust that keeps a spouse among the beneficiaries. It is demanding to draft and to administer, and it is not right for every couple. When a SLANT is the wrong tool.
A non-grantor QSBS trust, where the facts support it
A separate trust treated as its own taxpayer, which matters only for founders whose gain may exceed one Section 1202 cap. It works only if the stock qualifies and the trust is drafted, funded, and administered as a genuinely separate taxpayer. Where it works and where it fails.
Every engagement starts with the qualification review, so nothing is designed before we know what is and is not available. Some engagements end there, with a family plan and no trust beyond it.
A composite example. This is a fictional composite, not a real client or matter. It states no figures and no outcomes.
A founder and her spouse have two young children. Her company has been a C corporation since it was formed, and a priced round is being discussed. She has a will she wrote years ago and nothing else. The first conversation establishes what stock she holds and when each share was acquired, and the qualification review confirms whether it plausibly qualifies. If it does, the family plan comes first: a revocable trust, powers of attorney, health care directives, and a named guardian. Whether a spousal trust or a separate non-grantor trust belongs on top depends on the facts, and for many founders in this position it does not. She hears the answer either way, in writing, before any drafting begins.
Funding is a shared job, not a handoff
Funding is where most plans quietly fail, and it is not something a law firm can complete alone. Transfers require the owner's signature, and companies, custodians, and transfer agents each impose their own requirements. Our role is to prepare it, process what we can, and track it to completion, so nothing is assumed finished that is not.
The firm prepares and tracks
We draft the assignments, deeds, transfer forms, and letters of instruction. We engage directly with custodians, transfer agents, and registrars wherever they will accept us. We maintain a funding schedule showing every asset and its status and provide written confirmation of what was funded, what was deliberately left out, and why.
You sign and authorize
You sign what only an owner can sign. You provide account numbers, statements, and contacts, because we cannot retitle an asset we do not know exists. You complete the steps institutions accept only from the account holder, which often includes retirement accounts and employer plan designations. And you tell us when something changes.
Your company sets its own terms
Some steps depend on other people. Your company may need to waive transfer restrictions or rights of first refusal, obtain board or investor consent, reissue share certificates, and update the cap table. Custodians and transfer agents have their own forms and timelines, and some require a medallion signature guarantee. The firm will help you track these steps and work with you to ensure your plan is up to date and working with your corporate and other estate plan documents.
A trust is funded when the assets are actually in it. Getting there takes all three of us working together and communicating clearly from the start to prevent surprises in the end.
Knowing the Code is the baseline. Watching it is the job.
Founder planning is not a document you sign once. Statutes and regulations change, new rulings change how they are read, and your company and your family change too. We commit to working with you and your family from design through implementation, and afterward.
We read the primary sources
Positions are grounded in the statute, the regulations, and the rulings and cases that bring them to life. The authority a document relies on is recorded, so it can be re-checked when the law shifts rather than reinvestigated from scratch.
We monitor changes and tell you what they mean
When Section 1202 or the trust rules around it are amended, we look at what it means for the structures we have built and reach out where a client's position is affected. Not every change requires action. You should still hear about the ones that might.
We document the reasoning, not just the result
A structure that is questioned years later is defended with the contemporaneous record: why it was built this way, what was known at the time, and what the client decided. We create that record as we work.
We tell you when the answer is no
Some stock will not qualify. Some structures are not worth their cost or their irrevocability. Some founders are better served by a simpler plan. Saying so is part of keeping you in a defensible position.
Questions founders often ask
I don't expect to exceed the cap. Do I need any of this?
You may not need trust planning, and if so we will say so. You still need to know that the stock qualifies, where each tranche sits against the holding period, and that there is a basic estate plan behind it. For many founders under the cap, that is the whole engagement: a QSBS Qualification Review and a family plan, with no trust at all.
What if the company does better than I expect?
Then the planning question changes, and it is better to have asked it early. Transfers to family members or to trusts are valued when they are made, so the options are widest while the stock's value is still low. A review done now records where you stand, which makes it quicker to revisit after a strong round. It does not commit you to any structure.
What if we're acquired before year five?
It depends on when each share was acquired. For stock acquired after 4 July 2025, the exclusion is tiered: 50% after three years, 75% after four, and 100% after five. For stock acquired on or before that date, there is no exclusion unless the stock has been held more than five years.
In some cases a Section 1045 rollover, which defers gain by reinvesting the proceeds in other qualified small business stock, is worth evaluating. Whether it is available, and whether it makes sense, depends on your facts and on the deal.
I hold shares acquired both before and after 4 July 2025. What changes?
Each tranche is governed by the regime in force when it was acquired, with its own holding-period rule and its own figures, as the two regimes above set out. How the two interact for stock of the same company, and which shares to sell first if you have a choice, are among the things the review works through.
I started as an LLC and converted. Does that matter?
Yes. Stock received when an LLC converts to a C corporation can qualify, but generally the holding period starts at the conversion, and only gain that builds after the conversion is eligible for the exclusion. The conversion documents, the value at that date, and how the conversion was carried out all matter, so we ask for them early.
Is it too late if I already have a term sheet?
Usually not, but the available options are narrower and the cost of using them is higher, because transfers are valued at what the stock is worth when they happen. We would rather look at your facts than answer in the abstract. There is often useful work to do on documentation, entity hygiene, and the foundation plan even when the most aggressive structures are off the table.
Can you tell me how much this will save me?
No, and we would treat a confident answer to that question as a warning sign. The benefit available under Section 1202 depends on facts that are unresolved at the time planning is done: whether the company satisfies every requirement at every relevant moment, whether a sale occurs, in what form, at what price, under the law in force on that date, and how the structure is viewed if it is examined.
What we can tell you is what the statute makes available on facts like yours, what the structure would require of you, what it would cost, and where the risk sits.
Does my stock even qualify as QSBS?
That is the first question we answer, and it is not always yes. Qualification turns on the entity's form, whether the stock was acquired at original issue, the nature of the company's business, the company's gross assets immediately after the stock was issued, the company's redemption history, and how long you have held each tranche. Several of those are facts fixed in the past.
The numbers themselves also depend on when you acquired the stock, which is what the two regimes above set out. Where the answer is no, or unclear, we will tell you that directly, along with what, if anything, can still be done.
Why does it matter which state I live in?
Because the federal analysis is only part of it. Washington State is a community property state. The District of Columbia and Maryland are not. Maryland also imposes its own estate tax at a threshold well below the federal exemption, and levies an inheritance tax on certain beneficiaries, neither of which the federal exemption addresses. State law affects whether stock is separate or community property, where a trust can be administered, and what a transfer costs at the state level.
State taxes are a design input, not an afterthought. A structure that looks efficient federally can carry a state-level cost that was never weighed. Chad R. Vickery is admitted to practice in all three jurisdictions, which is why we can look at the whole picture rather than only the federal law.
I have counsel for my company already. How does that work?
Your corporate counsel represents the company; we represent you and your family. Planning that the corporate record does not support may not survive diligence, so we would rather coordinate with them from the beginning on transfer restrictions, board consents, stock certificates, and the cap table than hand everyone a surprise later.
How do your fees work?
We provide flat fees in writing before any drafting begins, not an hourly rate or an open-ended estimate. What the work costs depends on which structures actually fit your facts, how many entities and accounts are involved, and how much corporate cleanup the cap table needs, so fees are discussed on the first call, once the situation is clear.
The review itself is quoted up front too, so you are never billed into a decision you have not made. We are happy to talk about the range your situation is likely to fall into on the first call.
Is the Estate Plan Check-Up the right starting point for me?
It depends on your question. If it is about your equity, whether your stock qualifies, where your holding periods stand, or whether trust planning is worth doing, start with the QSBS Qualification Review.
If you already have a family estate plan and want to see whether it is funded and still fits, start with the free Estate Plan Check-Up. It runs in your browser and collects nothing. Many founders end up doing both.
Do you work with my CPA?
Yes, with your consent. Your CPA keeps the returns. We coordinate on basis, holding periods, valuation, and gift reporting, so the returns and the structure tell the same story.
Do you prepare tax returns?
No. We coordinate with your CPA, who prepares the returns, including any trust fiduciary or gift tax returns.
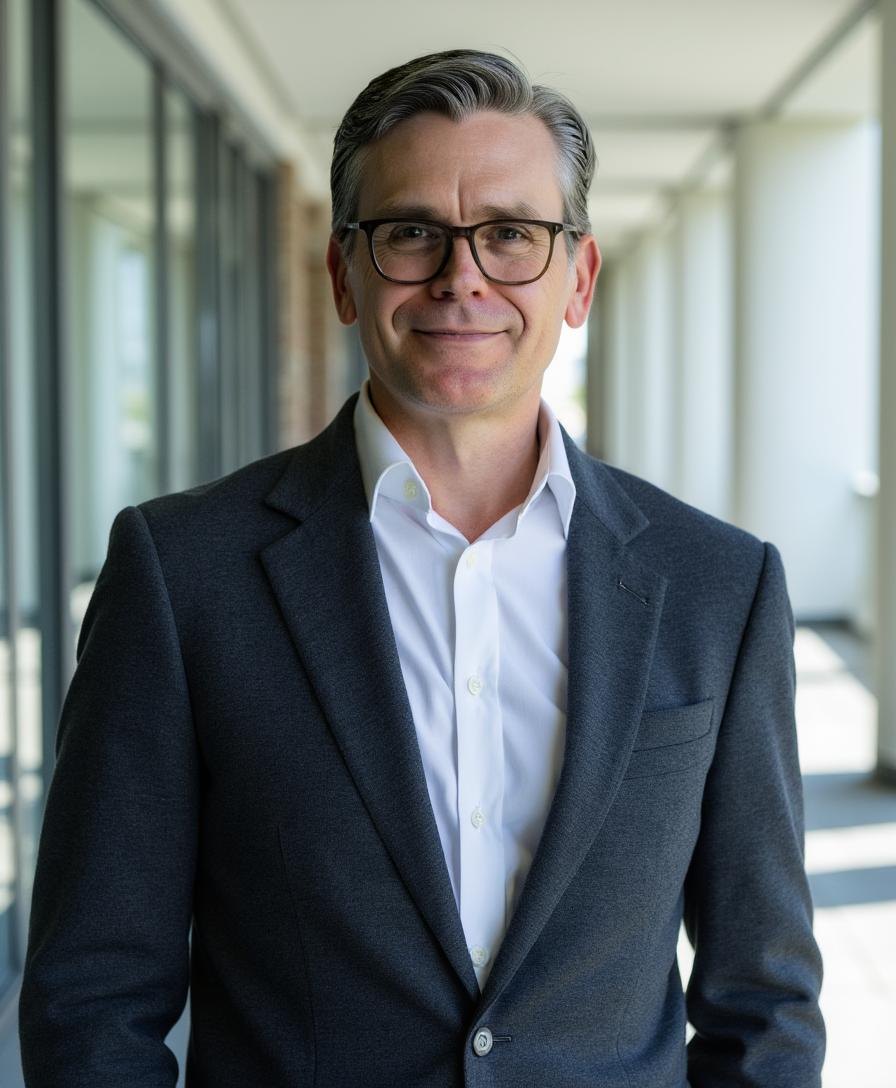
Your attorney: Chad R. Vickery
Every founder engagement is led personally by Chad. For two decades, he worked with national governments and institutions to interpret, implement, and track complex legal reform, turning new statutes into working procedures before deadlines that could not move. He brings that discipline to Section 1202: reading the statute closely, recording the reasoning behind each structure, and watching for the changes that affect it. Admitted in the District of Columbia, Maryland, and Washington State. The attorney you meet reviews, finalizes, and signs off on every document. Memberships include WealthCounsel, the Maryland State Bar Association's Estate and Trust Law Section, and the Washington State Bar Association's Real Property, Probate and Trust Section.
Find out whether your stock qualifies
The QSBS Qualification Review establishes what Section 1202 actually makes available on your facts, covering the entity, the stock, the holding periods, and your state, and what acting on it would involve. Quoted as a flat fee before it begins, and the answer is sometimes no.
Important notice. This page describes planning approaches that may be available under federal and state law as currently in effect. It is general information for educational purposes, not legal or tax advice, and it does not create an attorney-client relationship. Whether any structure described here is appropriate, or permitted, depends on facts specific to you, your company, and your state of residence, and tax law is subject to change, including with retroactive or prospective effect. No outcome, tax treatment, or result is promised or guaranteed. Prior results do not guarantee a similar outcome. Please consult us, or qualified counsel of your choosing, about your particular circumstances before acting.